Preparing a pitch to survive due diligence (article by Lina Taletavičiūtė-Misiūnienė)
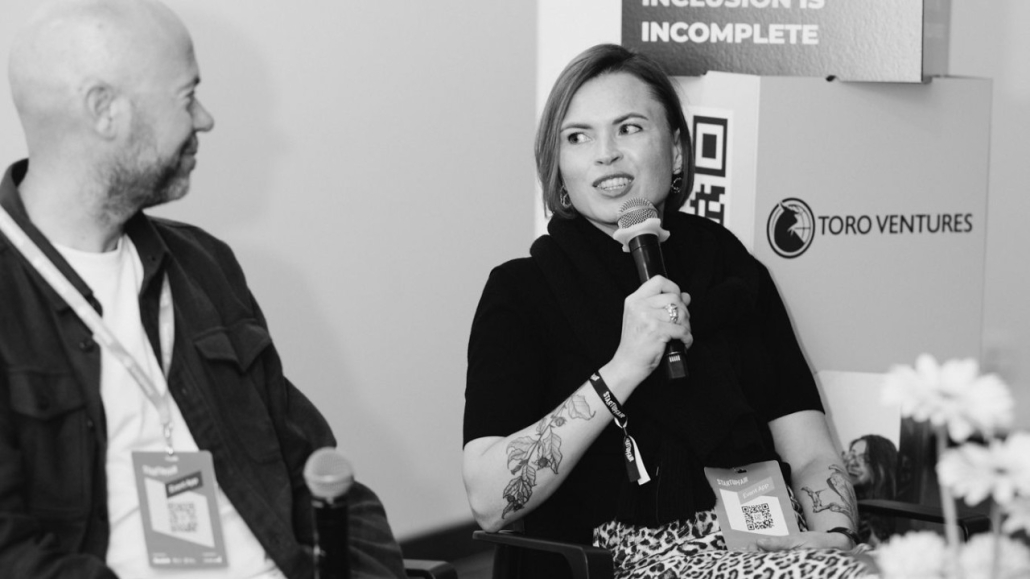
A week ago, I participated in a panel discussion at Startup Fair 2026 concerning communication between founders and investors. Speaking from a lawyer’s perspective, I emphasised that the information presented during a pitch should survive due diligence process.
Of course, a pitch should focus on the strengths of the business. Nevertheless, material statements made during the presentation should be supported by the company’s documents and should not create an impression that will later be contradicted by the data room.
The following matters should therefore be reviewed before approaching investors.
Statements made in the pitch
Founders should review the presentation slide by slide and identify the evidence supporting each material statement.
Claims concerning customers, revenue, partnerships, intellectual property, regulatory approvals and market size should be stated precisely. A pilot project should not be presented as a paying customer, an unsigned commercial opportunity should not be described as a concluded contract, and a patent application should not be presented as a granted patent.
The objective is not to remove all forward-looking statements from the pitch. Founders may present their expectations, provided that expectations, current facts and confirmed commitments are clearly distinguished.
Ownership of intellectual property
For a technology company, ownership of intellectual property is often central to the investment case. Before fundraising begins, founders should confirm that the company has obtained the necessary rights from every person or entity involved in developing its technology.
This review should cover intellectual property created by founders, employees, freelance developers, consultants, universities and research institutions. Payment for development services does not necessarily result in the automatic transfer of all intellectual property rights. Employment and contractor agreements should therefore contain appropriate assignment provisions, and any earlier gaps should be addressed through separate transfer documents where necessary.
If an ownership issue cannot be resolved before fundraising, it should be assessed with legal advisers and disclosed to the investor together with a realistic plan for resolving it.
Capitalisation and arrangements between founders
The capitalisation table presented to investors should correspond with the company’s official records. Founders should verify the legal ownership of shares, the proper documentation of all share issues and transfers, and the existence of any options, convertible instruments or other rights affecting ownership.
Particular attention should be given to informal promises of shares or options made to employees, advisers or contractors. What one party considers a preliminary discussion may be regarded by another as a binding commitment.
The founders should also have a written agreement governing their relationship. It should address ownership, roles, decision-making, vesting, founder departures, intellectual property and deadlock situations.
Disagreement between founders is not automatically a legal or investment problem. It becomes material when it affects decision-making, ownership, control over intellectual property or the continued involvement of a key founder.
Disclosure of material issues
A pitch does not need to describe every legal or operational difficulty encountered by the company. However, matters that could materially affect the business or the investor’s decision should not be withheld.
Such matters may include uncertainty over intellectual property ownership, disputes affecting ownership or control, material litigation, regulatory restrictions, significant contractual liabilities and inconsistencies in the cap table.
During the initial presentation, a material issue can usually be addressed briefly. The disclosure should be proportionate, but it should be made early enough to avoid giving the investor an inaccurate understanding of the company.
Preparation of the data room
The data room should be structured, current and consistent with the information presented during the pitch.
Depending on the company’s activities and stage of development, it should normally contain:
- corporate documents and shareholder records;
- an accurate capitalisation table;
- agreements with founders, employees and contractors;
- intellectual property documentation;
- material customer and supplier contracts;
- financial statements, management accounts and projections;
- regulatory documents;
- information concerning litigation and disputes.
Documents should be clearly named and organised. Executed documents should be distinguished from drafts and superseded versions.
An early-stage company may not have complete documentation in every area. The absence of a document is not necessarily fatal if the founders identify the gap, explain its significance and present a credible timetable for correcting it.
Final consistency review
Before presenting the pitch, don’t forget to make a final consistency review. Compare it with the company’s legal and financial records.
A pitch survives due diligence when the company described to investors is the same company evidenced by its records. This does not require the elimination of every risk before fundraising. It requires founders to understand the company’s material risks, resolve those that can be resolved, disclose those that remain and maintain consistency throughout the investment process.
